Your last round was priced at a number you cannot justify now, and you need more money. The two honest ways through are a bridge to grow into the price or a down round to reset it. Which one is right turns on a single question.
Venture debt can look like the cheapest money you will raise. But the lender is underwriting one thing above all: whether you will raise your next equity round. Understand that and you will know when to take it and when to leave it.
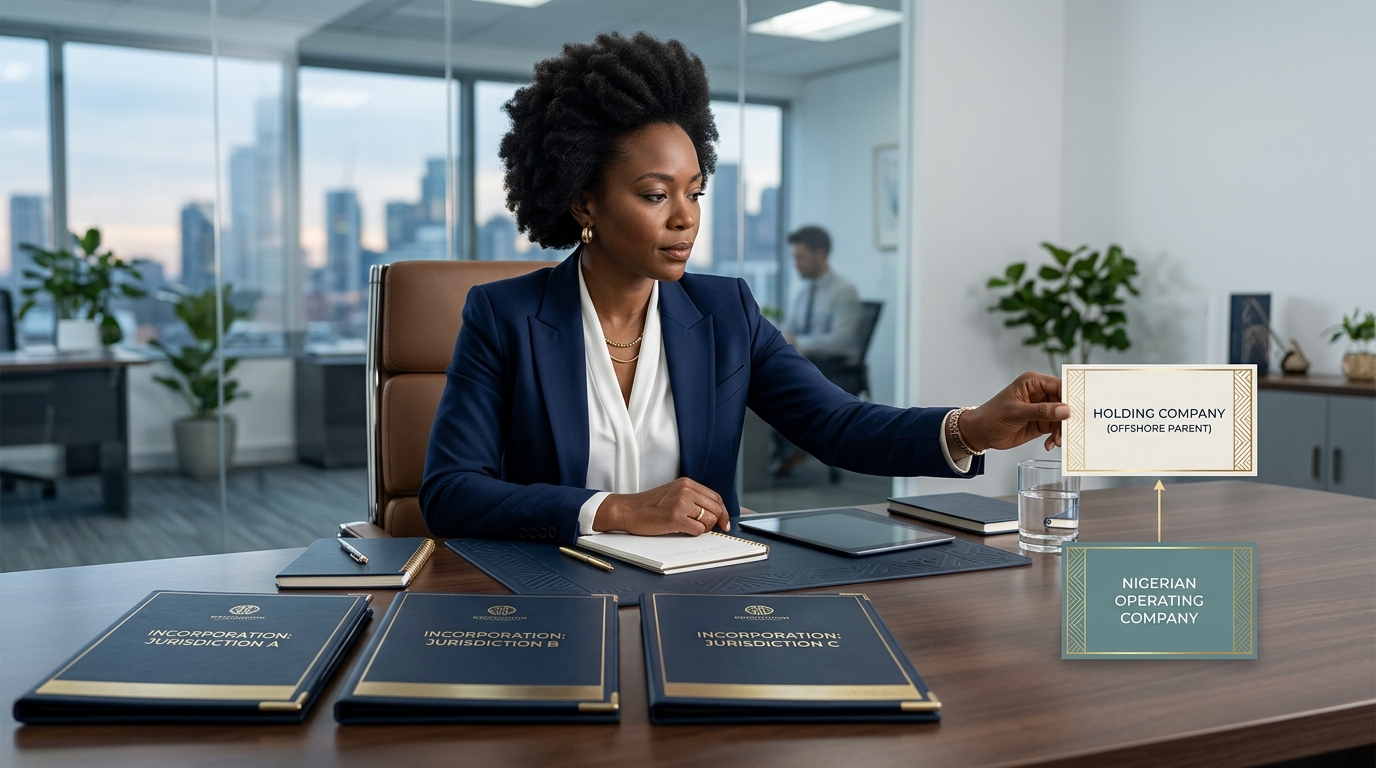
You raised internationally and flipped to a parent company abroad, in the US or the UK, over your Nigerian company. Now which one bills the customer, which one employs the team, and who pays whom? The money and costs between the two have to move deliberately, and on the record.
The finances usually get a proper look once a month, when the books close. But a small set of numbers moves fast enough that monthly is too slow. Watching them weekly, for a few minutes, is one of the most useful habits a founder can build.
Your first board meeting sets the tone for every one after it. Run it off a pack the room has already read, spend the time on the decisions that need the board, and be straight about what is not working. Done well, it turns the board into a resource rather than an audience.
Closing a round is a skill. Deploying it is a different one. Here is how to turn a fixed sum into enough progress to reach your next stage, using burn, runway, the burn multiple, and one test: whether you would reach profitability before the money runs out.
Most founder budgets are built on a single growth rate with nothing underneath it, and an experienced board sees through it in a minute. A budget they trust is built a particular way, from the plan, from real drivers, and honest about its assumptions.
The money has landed and the pressure is to start spending it. The first quarter is where you either build the discipline that makes the round last or spend it down faster than you meant to. What to put in place first, before the spending starts.
Most founders ask whether they can afford a CFO. The sharper question is whether the business has started making decisions its numbers cannot yet support. Here is how to tell where you stand.
If your startup moves, holds or lends money, the question is which Central Bank of Nigeria licence you need and when, not whether. Here are the main categories, what each permits, the capital they require, and how founders launch legally before they can afford their own.
Investors verify the numbers behind your deck before they invest. Here is what investor-ready books look like, the gap between having revenue and proving it, and how to close it before a raise rather than during one.
Most investor-readiness advice is written for a founder in San Francisco and omits the three things that most often stop African deals. Here is what readiness actually requires, and how to test whether you have it.
If you live in the US, the UK or Europe and run a Nigerian company, paying yourself is a cross-border tax question with a different answer in each country. Here is where your pay is taxed, salary versus dividends, and the traps that catch diaspora founders.
How to divide founder equity by real contribution, why vesting with a cliff protects everyone, how much to set aside for team and advisors, and why the split belongs in a written founder agreement.
Founder pay is a runway decision. Set it too low and your judgement suffers; set it too high and you shorten your runway and unsettle investors. Here is a framework for setting the number, what the benchmarks show, and how to take the money so the tax and the books stay clean.
Nigeria's Tax Act 2025 took effect on 1 January 2026 and raised the threshold below which a company pays no income tax. Here is what your company now owes, how tax applies across borders, and the filing obligations founders most often miss.
Receiving dollars, holding value against a falling naira, paying people abroad, and getting profits back out. Here is how cross-border money works for founders in Nigeria, and the one document that decides whether your money can leave.
Where you register your company is one of the few early decisions that is hard to reverse. Here is how to weigh Nigeria, the UK and a Delaware parent, what "the flip" is, what it costs, and when it is worth doing.
A term sheet is where a funding deal is really made. Here are the economic and control clauses that matter most, from liquidation preferences and the option pool shuffle to board seats and anti-dilution, in plain English.
Venture debt buys more runway with far less dilution than raising more equity, but it is debt and behaves like debt when things get hard. Here is how it is sized and priced, how lenders decide, when it fits, and the risks founders underweight.
Three ways to raise, three sets of trade-offs. A clear comparison of SAFEs, convertible notes and priced rounds, and a simple guide to which fits your stage, your amount and your investors.
A priced round sets a valuation and issues shares today. Here is how the round is built, the preferred-share terms that decide what you keep in a good exit and a bad one, and what to hold the line on.
Convertible notes have fallen to just 7% of US pre-seed rounds, but they are far from dead, especially in Africa. Here is how interest, maturity, caps and discounts work, what the data says, and how a note differs from a SAFE.
SAFEs now account for 93% of US pre-seed rounds. Here is how caps, discounts and the post-money structure actually work, what the data says, with a worked example and the traps to avoid, including what changes in Africa.
Series D is raised either to accelerate a rocket or to buy time to a better exit. Here is what the two stories mean, who invests at this late stage, and what belongs in a Series D pitch deck.
Series C funds market leadership: aggressive expansion, acquisitions and the road toward an exit. Here is what late-stage investors underwrite, the metrics bar, and what belongs in a Series C pitch deck.
Series B funds scale: expanding a proven engine into new markets, segments and products. Here is what investors underwrite at this stage, and what belongs in a Series B pitch deck.
Series A funds a repeatable growth engine. Here is the metrics bar investors hold you to, why so many companies stall here, and what belongs in a Series A pitch deck.
Seed funds the search for product-market fit. Here is what investors look for once you have a live product, the traction that matters, and what belongs in a seed-stage pitch deck.
Pre-seed funds the idea before there is much to show. Here is what the stage is really for, what the earliest investors look for, and exactly what belongs in a pre-seed pitch deck.
Valuation is the most argued-over number in fundraising and the least understood. Here is what pre-money and post-money really mean, how early-stage valuations are actually set, and what genuinely moves the number.
Every round you raise changes who owns your company. Here is how a cap table works, how dilution really adds up across rounds, and the levers that decide whether founders keep a meaningful stake by the end.
Investors spend about two and a half minutes on a pitch deck, and nearly half never reach the last slide. Here is what a deck is for, the 10 slides that raise, and how each one changes by stage.
A warm introduction converts up to three times better than a cold email. Here is how to find the right investors, build the introductions that get meetings, and run outreach that respects your time and theirs.
A third of deals collapse at the final hurdle over preventable gaps. Here is what happens in due diligence, what belongs in your data room, and how to prepare so a signed term sheet actually becomes money in the bank.
African tech raised $4.1 billion in 2025, but the money concentrates in four countries, one sector, and increasingly in debt. Here is what makes raising on the continent different, and how founders can prepare to stand out.
Growth only helps if each sale makes money. Unit economics is the small piece of arithmetic that tells you whether to press the accelerator or fix the engine first.
You can be profitable on paper and still miss payroll. The gap is working capital: the cash trapped between paying your suppliers and collecting from your customers.
Price is the fastest lever you have on profit, and the one founders touch least. Here is how to raise it with confidence, and why a small increase does more than a big sales push.
When your costs are in dollars and your revenue is in naira, a falling currency quietly eats your margin. Here is how to see the exposure and build a business that holds up when the rate moves against you.
The monthly investor update is the highest-return hour a founder spends. Done well, it turns backers into a second team. Done badly, or not at all, it lets the relationship, and the next cheque, go cold.
By Olubunmi Nmerenu, ACA
The CFO Briefing
Financial intelligence for African founders. Monthly.
Original data, practical frameworks, and the numbers that actually move a business. Free to join, and no noise.